
Related Insights
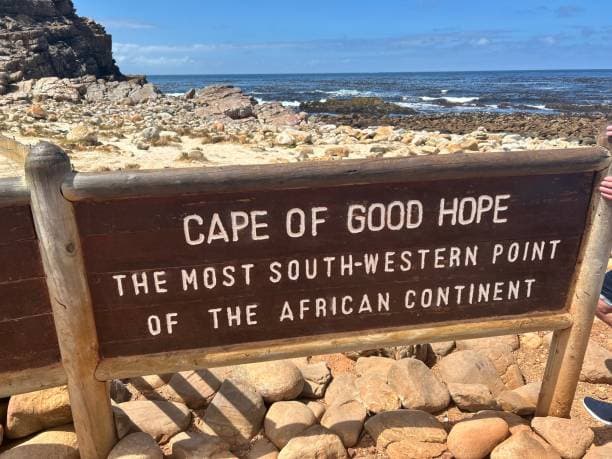
Cape of Good Hope Routing: July 10 Updated Cost Assessment
The latest Cape of Good Hope routing update released on Friday, July 10, reveals a nuanced shift in freight costs for Asia‑Europe chemical shipments. Bunker Adjustment Factors and the recent BAF reset have reshaped container shipping rates, impacting procurement decisions across the supply chain.
Doha Talks Today: What US-Iran Negotiations Mean for Chemical Shipping Logistics and Global Procurement
Today's Doha talks could reshape chemical shipping logistics across the Gulf. With elevated maritime risk, delayed vessel movements and cautious carrier policies, procurement teams need to understand how today's diplomatic outcome could affect Q3 sourcing, freight costs and supply chain planning.
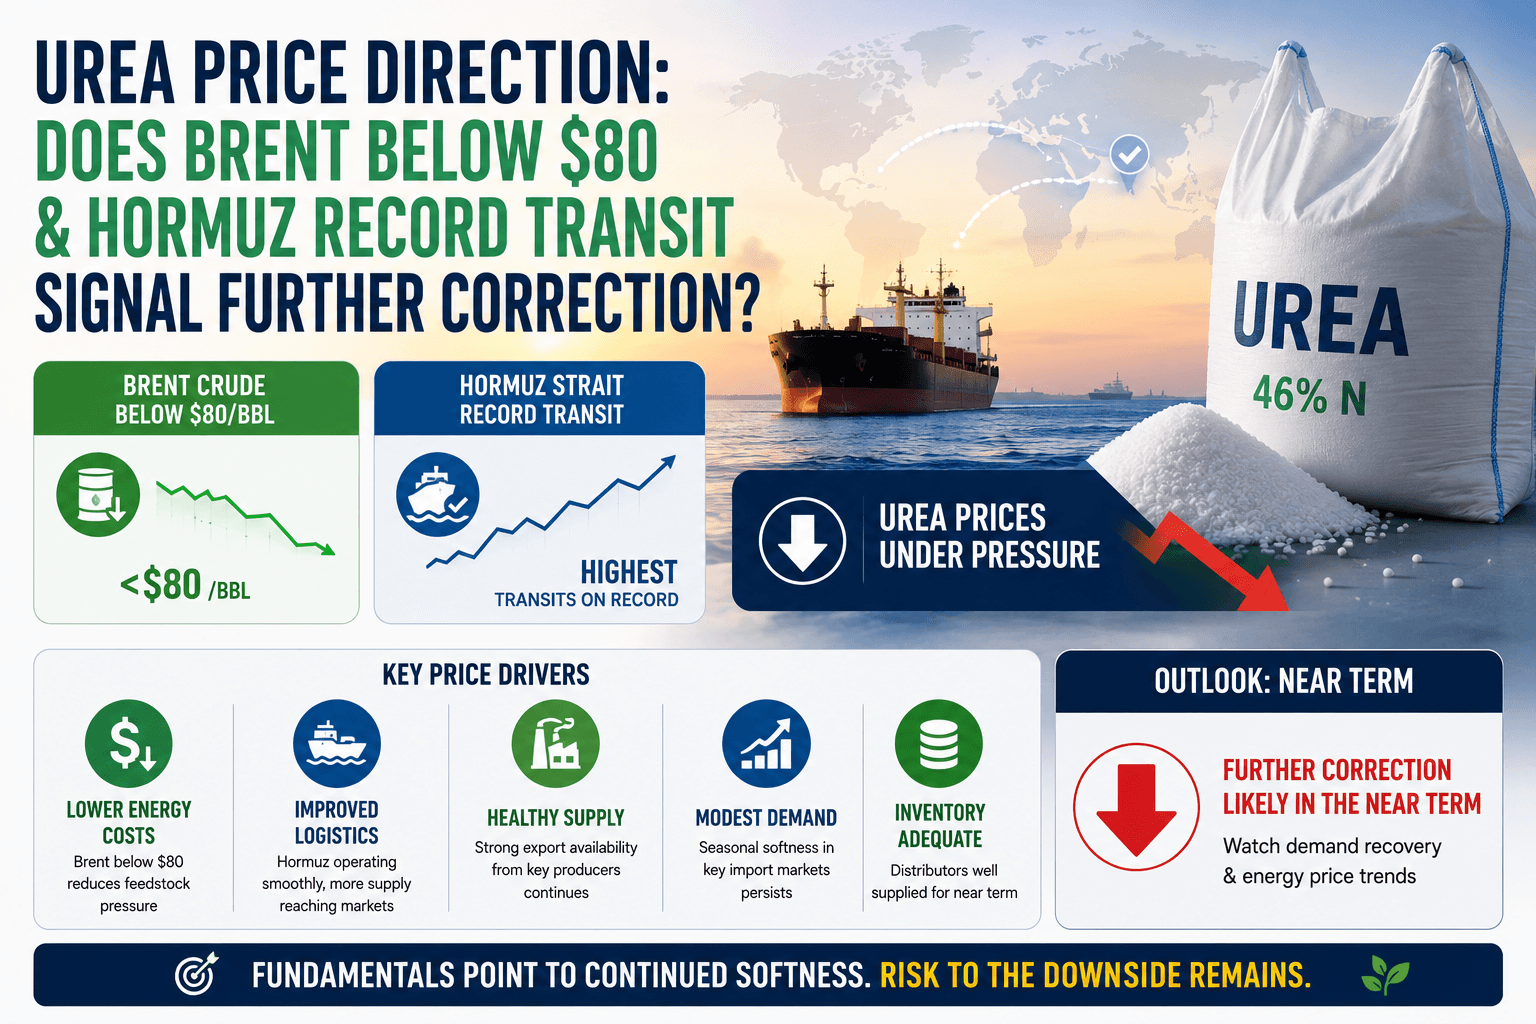
Urea Price Direction: Does Brent Below $80 and Hormuz Record Transit Signal Further Correction?
Urea prices have already fallen 36% from April highs, but improving Hormuz shipping and lower Brent crude suggest only modest further correction ahead. For fertilizer buyers, the strongest buying opportunity may already be unfolding before Q3 market stabilization begins.
Why Brent Is $72.60 Despite Active Drone Strikes: What the June 29, 2026 Oil Market Paradox Means for Chemical Buyers
Brent crude has dropped to $72.60 despite ongoing military escalation across the Gulf. This unusual market reaction signals that supply recovery currently outweighs geopolitical risk, creating important implications for petrochemical procurement and chemical pricing in the months ahead.
Agrochemical Logistics 2026: Cape Route vs Hormuz Corridor
Shippers face a critical routing decision in Q3 2026, weighing the Cape Route’s faster transit against the Hormuz Corridor’s higher insurance costs. Freight rates, geopolitical risk, and delivery windows differ, impacting fertilizer shipping profitability.
Formaldehyde Market Outlook Q3 2026: Methanol Cost Relief Emerges but Resin Price Adjustments Will Take Time
Formaldehyde producers may finally see feedstock cost pressure ease as methanol supply conditions improve and crude oil prices remain softer. However, buyers of urea-formaldehyde and phenol-formaldehyde resins should not expect immediate price reductions, as contract structures and inventory cycles will delay market adjustments into August 2026.
Don't miss out on our updates! Subscribe to our newsletter now
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.