
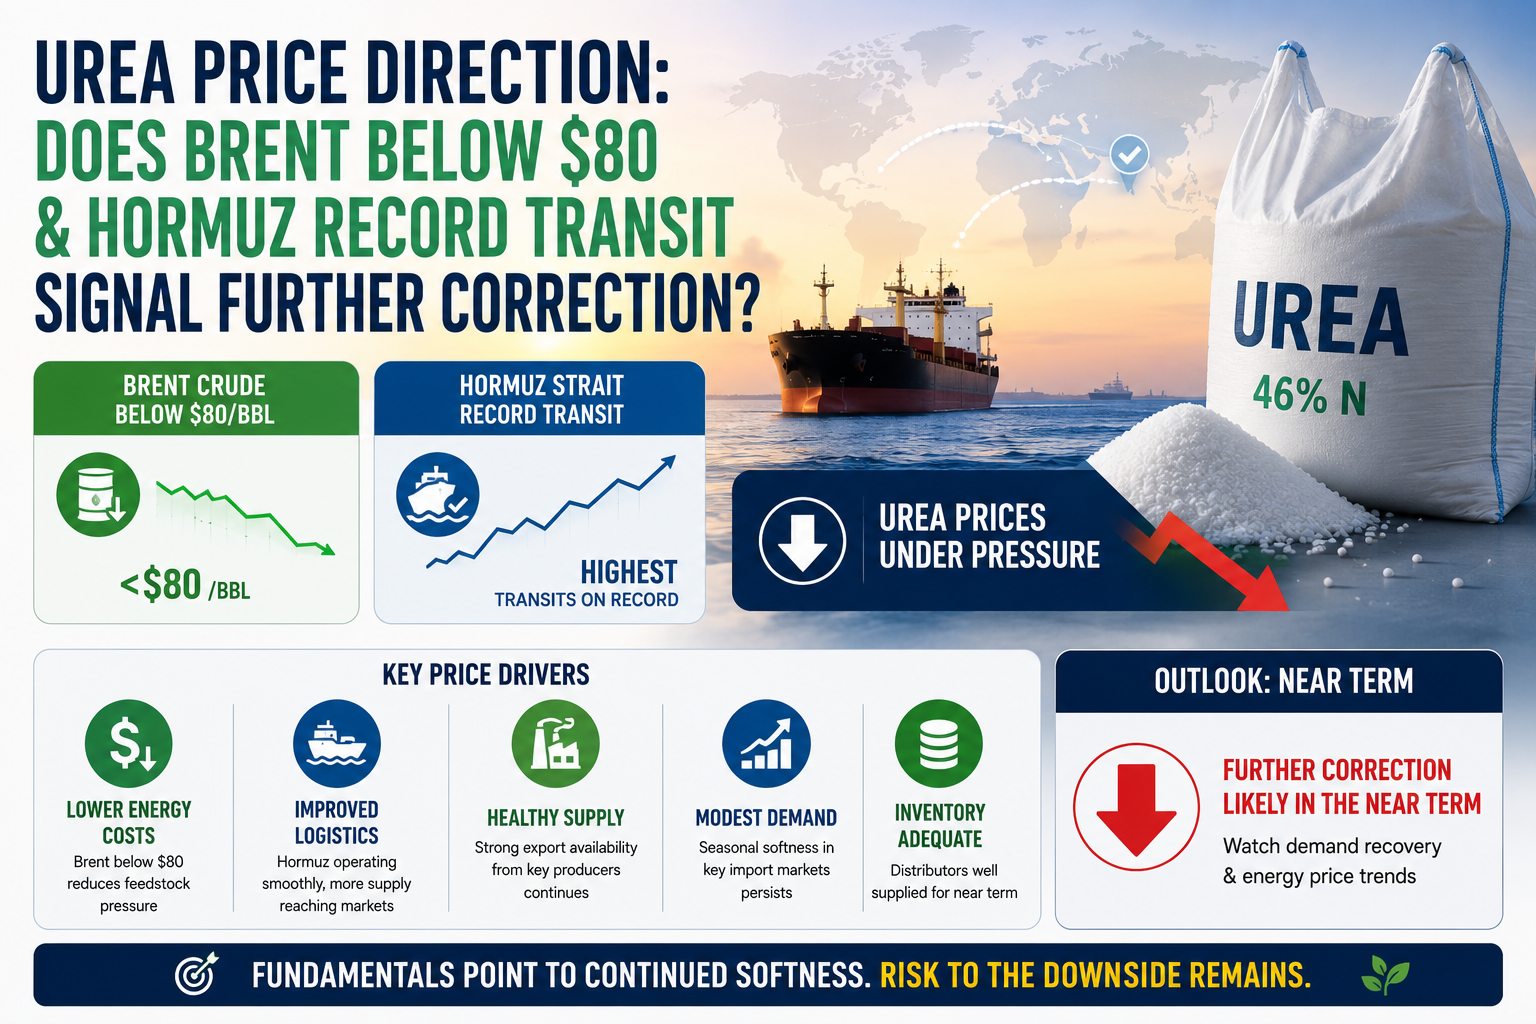
Urea (Granular) - Egypt CAS: 57-13-6
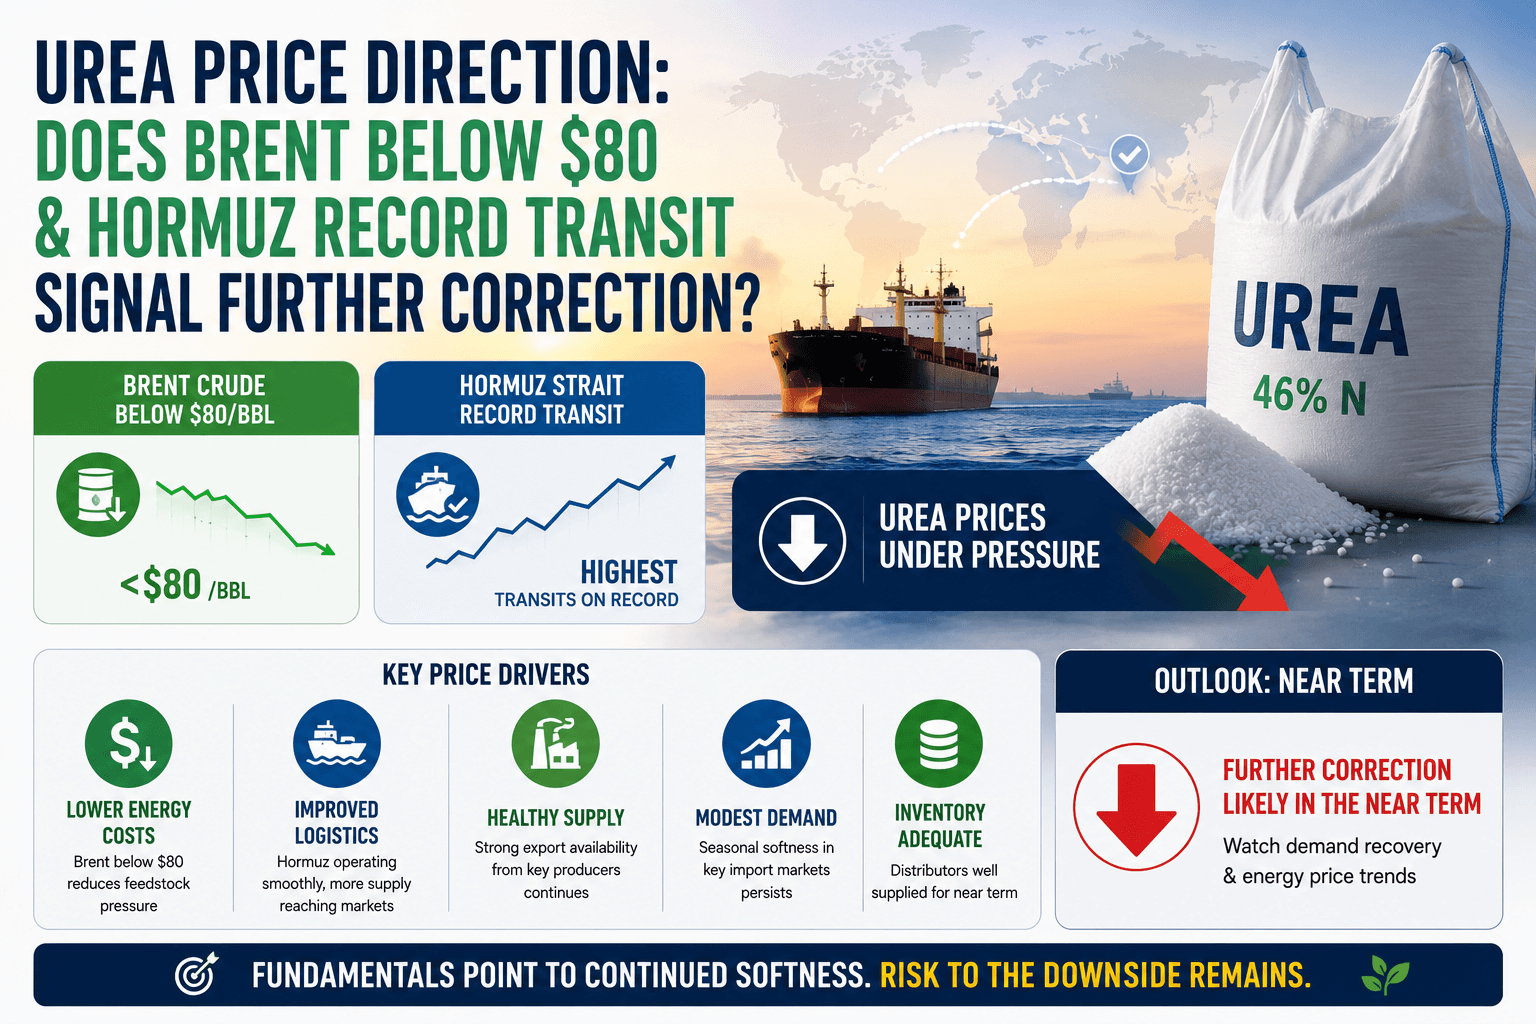
Urea (Granular) - Egypt CAS: 57-13-6
Refrigerant R22 prices surged by more than 2,000 yuan per tonne within a single week during July 2026, drawing attention across China's chemical market. Procurement teams should understand what such rapid movements may signal for refrigerant supply, industrial demand and purchasing strategies.
Brent crude price swings have a direct impact on the cost premium of green există hydrogen compared to its grey counterpart. With Brent at $79, the economics of green hydrogen shift dramatically, influencing low‑carbon chemical procurement and the broader energy transition. This article explores the mechanics behind the premium calculation and its implications for the chemical industry.
Caustic soda and soda ash markets closed H1 2026 with more stable conditions compared with several crisis-affected chemical segments. Buyers can use current trends as a reference point for H2 procurement planning and cost assessments.
Brent crude price stability at $74.06 is giving chemical buyers a temporary reference point for Q3 contract planning. Procurement teams are watching energy markets closely as Gulf supply risks continue to influence commodity chemical pricing.
Urea prices in 2026 are poised for a rebound as Gulf exports climb back to 75% of pre‑war levels. This shift reshapes demand in the Southern Hemisphere, offering new buying windows for fertilizer importers. TradeAsia tracks the latest market dynamics for SABIC and QAFCO urea.
The end of India’s fertilizer duty waiver and the launch of the MMTC Q3 tender are reshaping procurement strategies for urea and DAP. Farmers, importers and policy makers are recalibrating expectations as pricing volatility rises. This article dissects the key drivers and market implications.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.