Industry Landscape and Key Players
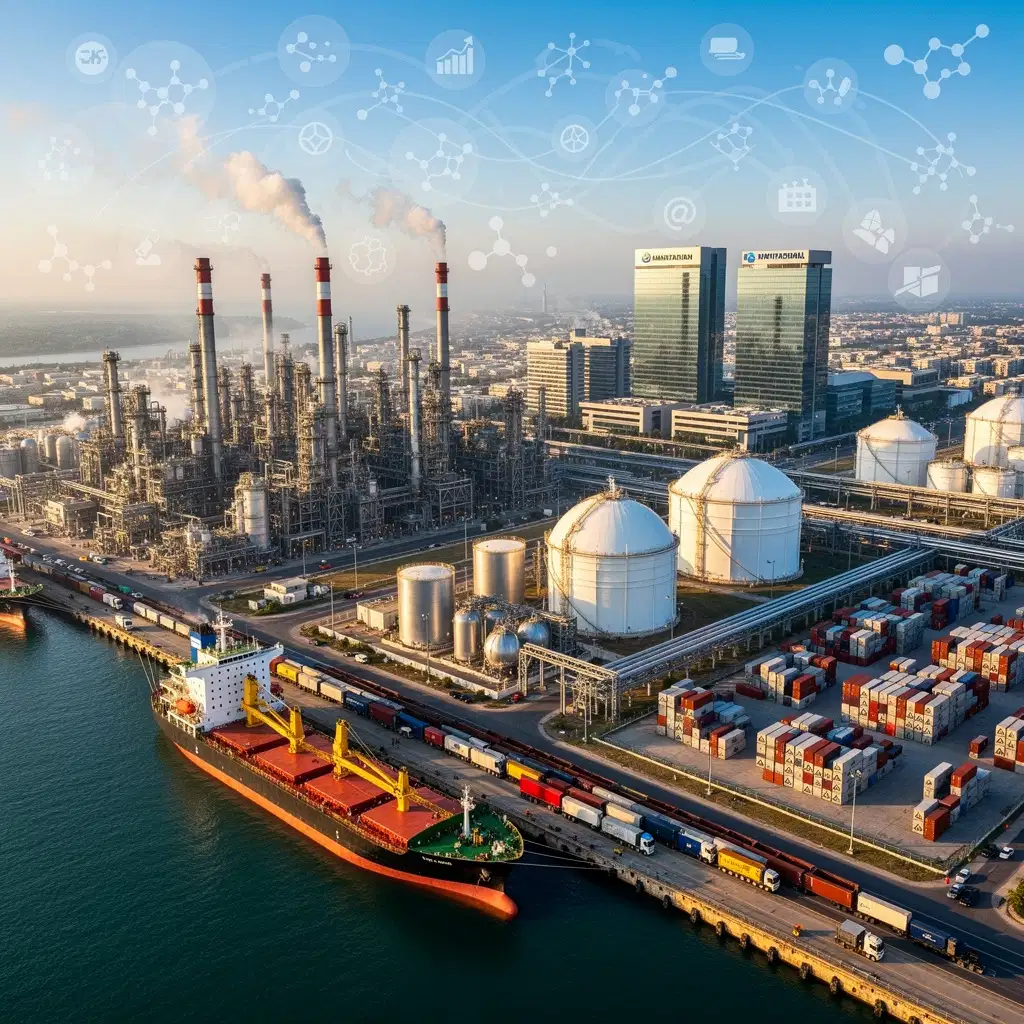
The South African chemical sector is underpinned by a highly integrated value chain that spans from upstream feedstock production to downstream specialty chemicals. Sasol, founded in 1950, remains the flagship producer, churning out roughly 4 million tonnes of chemicals annually from its Secunda and Sasolburg Fischer‑Tropsch complexes. These facilities generate synthetic fuels, waxes, solvents, ammonia and a broad spectrum of polymers that feed national and regional demand.
Mining Chemicals: The Primary Engine
The mining sector, a cornerstone of the South African economy, relies heavily on a suite of chemicals. These include collectors, frothers and flocculants for gold, platinum and coal extraction. The demand for these materials has remained steady, driven by global commodity prices and the country’s status as a leading producer of precious metals.
Water Treatment: A Growing Need
Chronic water scarcity across the continent pushes mining and industrial operations to invest in advanced treatment solutions. Coagulants and biocides are particularly in demand, ensuring compliance with stringent environmental regulations while maintaining operational efficiency.
Surfactants and Specialty Products
Sasol’s Performance Chemicals division has carved out a niche as a global surfactants player, supplying products used in detergents, emulsifiers and surface‑active applications. This segment complements the bulk chemical production and offers higher margins.

Challenges: Electricity Constraints and Load‑Shedding
Electricity supply remains the predominant bottleneck. Intermittent load‑shedding disrupts continuous production runs, forcing plants to cycle on and off. This instability not only reduces throughput but also increases operational costs and product variability.
As a result, many South African buyers have turned to imports of specialty intermediates and battery materials from Asia and Europe to maintain product quality and supply reliability.
Strategic Responses for 2026
Local Sourcing of Base Chemicals – Prioritize procurement from Sasol to take advantage of the deep value chain and reduce reliance on imports.
Dual Sourcing for Specialty Items – Maintain backup suppliers in Asia and Europe for critical intermediates that are sensitive to power interruptions.
60‑Day Safety Stock for Winter Peaks – Build inventory buffers ahead of seasonal power shortages to avoid production halts.
Energy Efficiency Upgrades – Invest in renewable energy installations and process optimization to mitigate load‑shedding impact.
Collaborative Power Agreements – Engage with national grid operators and local municipalities to secure preferential power contracts for essential industrial users.
Market Outlook and Growth Opportunities
Despite the power challenges, the South African chemical market is poised for moderate growth. Key growth levers include:
Expansion of mining projects in the northern provinces, increasing demand for collectors and frothers.
Growing emphasis on water treatment solutions as global sustainability standards tighten.
Diversification of Sasol’s product portfolio into higher‑margin specialty chemicals.
Potential for regional export of base chemicals to neighboring African markets.
Conclusion
The South African chemical market remains a critical engine for the continent, supported by Sasol’s extensive infrastructure and the robust demand from mining and water treatment sectors. By adopting a dual sourcing strategy, building safety stocks, and investing in energy resilience, businesses can navigate electricity constraints and capitalize on emerging opportunities in 2026 and beyond.