
Citrus Pulp CAS: 94266-47-4
Citrus Pulp CAS: 94266-47-4
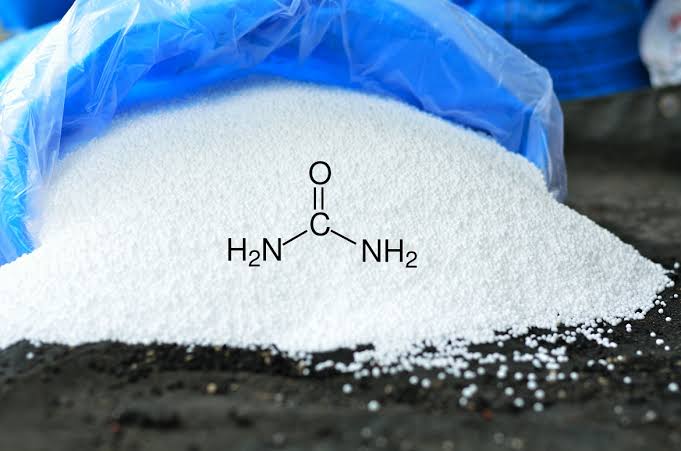
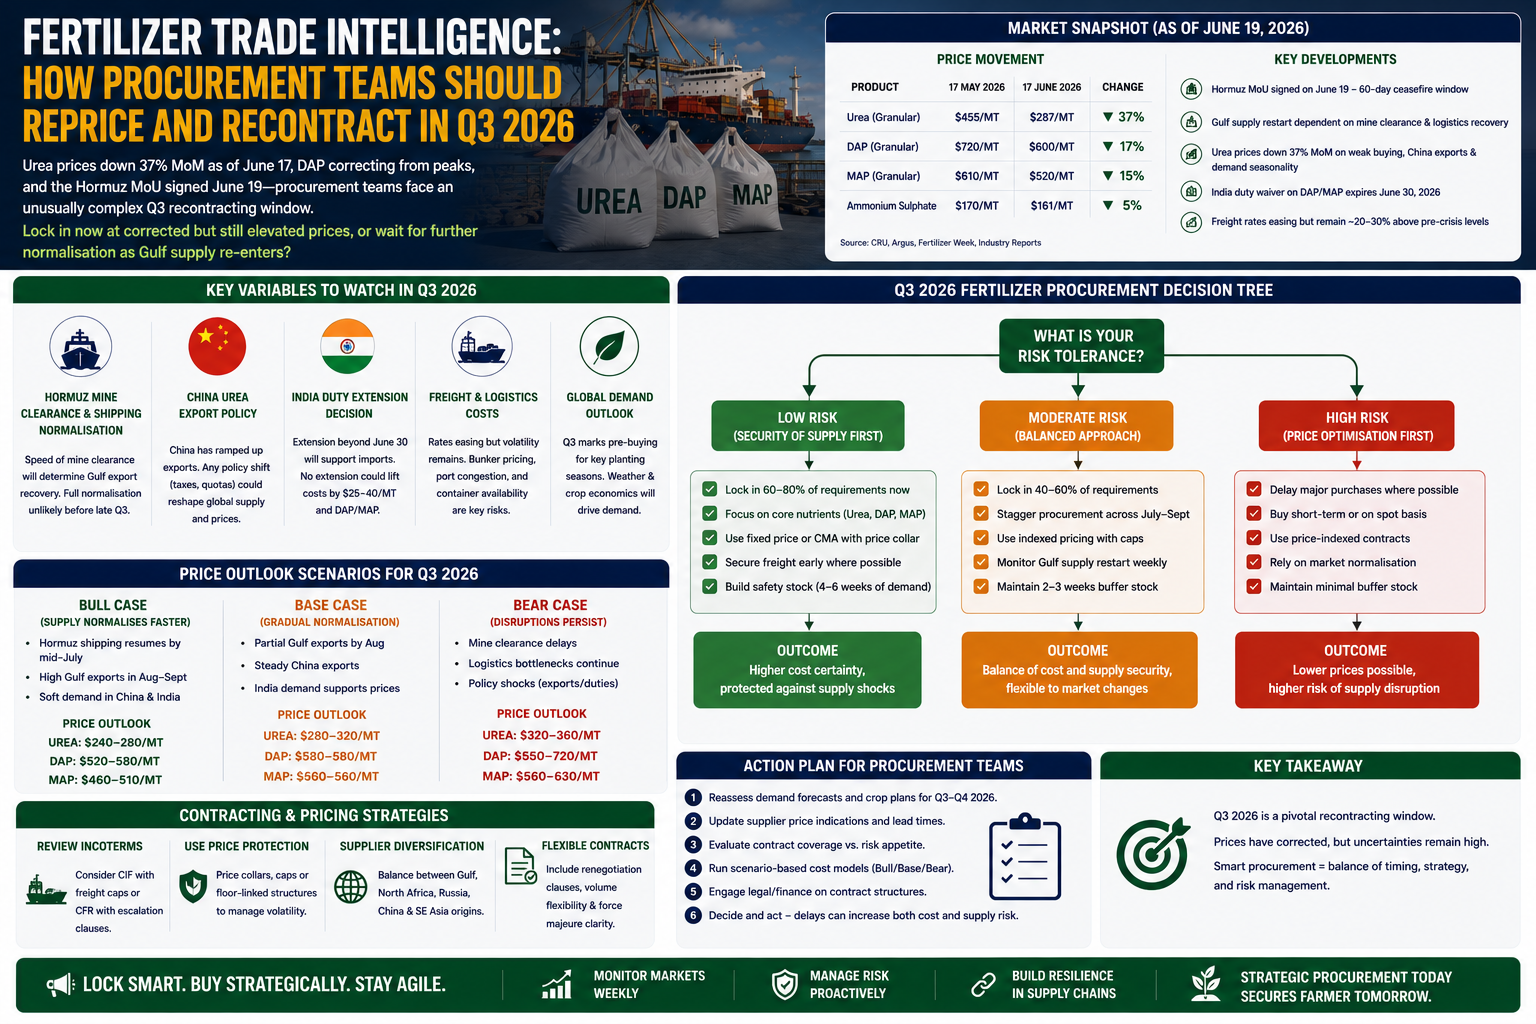
This week's agrochemical intelligence highlights fertilizer supply recovery, phosphate pricing, urea market developments, Bangladesh's ammonia restart, and upcoming EU trade decisions that could reshape procurement strategies during Q3 2026.
The Hormuz crisis disrupted nearly 45% of global sulfur supply as Gulf refinery by-product exports collapsed for months. With vessel movement now improving, sulfur and sulfuric acid buyers may finally see the first meaningful cost relief in August after one of 2026’s most overlooked supply chain disruptions.
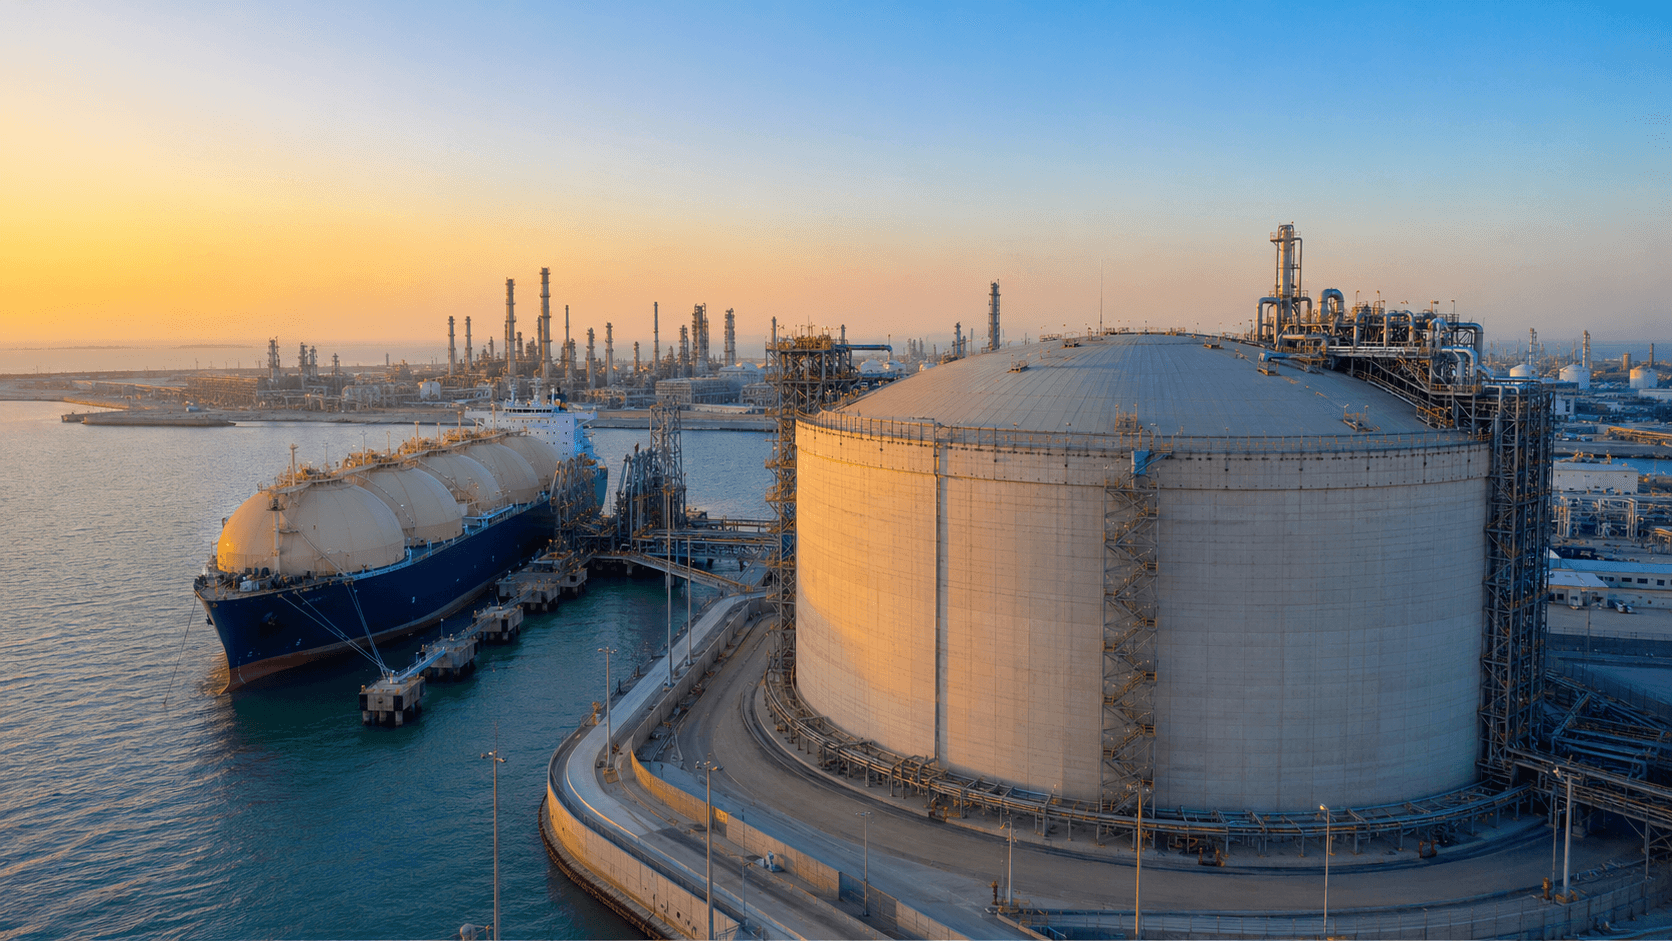
Qatar enters H2 2026 balancing diplomacy, industrial recovery and global investment strategy. As Doha hosts technical negotiations and Ras Laffan begins a long reconstruction process, buyers should monitor Qatar's own commercial decisions for the clearest signals of regional stabilisation.
China’s urea export limits and aggressive methanol-to-olefins (MTO) rates set the stage for 2026 chemical flows. July pricing decisions will reveal whether China will defend its crisis‑era share or recalibrate toward market balance. Global buyers must watch China’s export strategy closely.

H1 2026 closes with simultaneous trade policy changes across India, the EU and the US. Chemical procurement teams face overlapping tariff, anti-dumping and regulatory fee developments that require structured multi-jurisdiction tracking.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.